


Germany: Federal Cabinet unveils draft 2027 income tax reform, splits trade tax revenue for data centre companies
Germany’s Ministry of Finance has published the Draft Income Tax Reform Act 2027 (Einkommensteuerreformgesetz 2027), which was approved by the Federal Cabinet on 2 September 2026. The draft outlines a proposal from the German Federal Ministry
See More
Finland proposes reduced corporate tax rate in 2027 budget
Finland’s government has announced the 2027 budget proposal, on 1 September 2026, with the intention to stimulate the economy through targeted tax cuts for low- and middle-income earners and a significant reduction in the corporate tax rate to
See More
Vietnam: National Assembly passes two-year income tax relief for individuals, enterprises
Vietnam's National Assembly has adopted a resolution cutting personal income tax and corporate income tax by 30% for eligible individuals and enterprises during the 2026 and 2027 tax periods. The 16th National Assembly passed Resolution No.
See More
Italy confirms tax exemption for business transferees after failed restructuring
The Italian Revenue Agency clarified on 1 September 2026 that a business transferee retains full tax exemption even after a restructuring agreement fails due to the transferor's breach of contract. The ruling, contained in Legal Advice No. 9 of 1
See More
France updates income tax reduction guidance for SME investments
France’s tax authority has updated its guidance on income tax reductions for investments in small and medium-sized enterprises (SMEs), FCPI and FIP funds, and solidarity-based enterprises of social utility (ESUS). The update published on 27
See More
France introduces tax neutrality for enterprise restructuring
France has clarified, on 19 August 2026, the tax treatment of sole proprietorship restructuring where an individual entrepreneur elects for Corporate Income Tax (IS), introducing optional mechanisms to defer, suspend or spread taxation of capital
See More
Lithuania proposes 200% corporate tax deductions for investments in select advanced technologies
Lithuania is proposing a 200% tax deduction for companies investing in certain advanced technologies under draft amendments to the Law on Corporate Profit Tax published on 25 August 2026. The proposal would allow entities implementing investment
See More
Lithuania: VMI clarifies rules on foreign tax deductions
Lithuania’s State Tax Inspectorate (VMI) has updated its official commentary on the Law on Corporate Income Tax, clarifying how corporate income tax or an equivalent tax paid abroad can be deducted from Lithuanian corporate income tax. The
See More
Ireland updates Section 110 guidance on foreign withholding tax
Irish Revenue has updated its guidance on the tax treatment of foreign withholding tax for Section 110 qualifying companies, setting out how relief may be available under Schedule 24 where income has been taxed at source in another
See More
US: IRS clarifies limitation on deduction for business interest expense
The US IRS has published updated Questions and Answers about the limitation on the deduction for business interest expense, dated 19 August 2026. The updated FAQs are as follows: Topic A: General information Q1. What is the section 163(j)
See More
Australia: Senate passes tax reform bill introducing permanent loss carry-back, AUD 20,000 asset write-off
The Australian Senate approved the Treasury Laws Amendment (Tax Reform No. 2) Bill 2026 on 19 August 2026, following its passage by the House of Representatives on 18 August 2026. The Bill is a legislative package designed to implement key
See More
Poland proposes 22% CIT rate for large companies in tax reform package
Poland’s government has unveiled a package of tax changes that would increase the basic CIT rate to 22% for entities with annual revenues exceeding EUR 50 million and for tax capital groups, while introducing changes to several other tax
See More
Germany: Federal Fiscal Court clarifies minimum taxation, loss carryforwards
Germany’s Federal Fiscal Court (BFH) has confirmed the constitutionality of statutory minimum taxation rules while finding that tax authorities must reconsider a request for equitable relief where restrictions on loss carryforwards create a
See More
Brazil announces deadline to apply for the Simplified National Tax Regime
Brazil's Federal Revenue Service (RFB) announced, on 19 August 2026, that companies wishing to join the Simplified National Tax Regime (Simples Nacional) must submit applications in September 2026 rather than January 2027. The change stems from
See More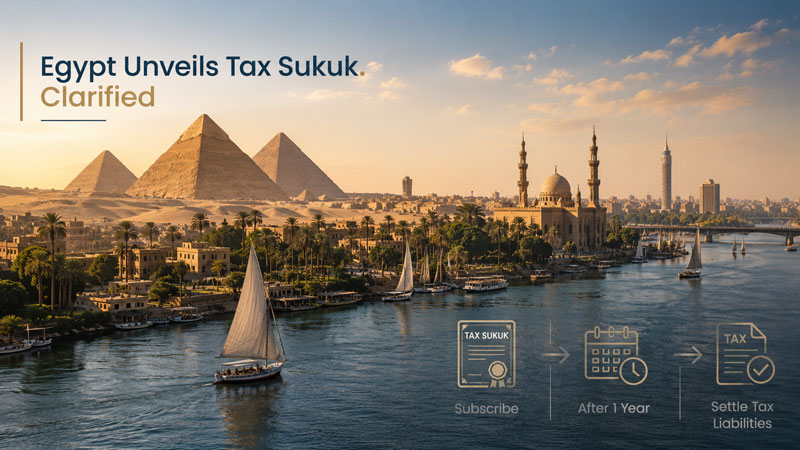
Egypt: ETA unveils plans introduction of tax Sukuk
Egypt is preparing to introduce an optional Tax Sukuk that taxpayers can subscribe to and later use to settle future tax liabilities, as the government seeks to raise domestic liquidity and encourage tax compliance. The Egypt Tax Authority (ETA)
See More
India publishes disclosure scheme rules for foreign assets of small taxpayers
The Indian Central Board of Direct Taxes (CBDT) Ministry of Finance, notified the Foreign Assets of Small Taxpayers - Disclosure Scheme Rules, 2026 on 14 August 2026, under Section 143 of the Finance Act, 2026. The rules provide the procedural
See More
New Zealand clarifies corporate income tax treatment of amalgamations
New Zealand Inland Revenue issued Technical Decision Summary No. 26/11 on 14 August 2026, setting out the corporate income tax consequences of a proposed amalgamation involving several New Zealand resident companies under common ownership. The
See More
Taiwan clarifies business tax rules for non-profits selling goods or services
Taiwan's National Taxation Bureau of the Central Area has clarified how non-profit educational, cultural, public welfare and charitable institutions must report and pay business tax when they sell goods or services, following an enquiry from an
See More