


Japan’s 2016 tax reform was enacted on 29 March 2016 and at the end of April 2016, the National Tax Agency posted guidance on its website to help clarify the documentation requirements within Japan. The tax reform also implements penalties for a failure to file the CbC report by the due date which is up to a maximum of JPY300,000. This penalty can be levied on the representative, proxy or responsible employee, and additionally on the company itself.


Related Posts
OECD updates MLI arbitration profiles for Australia, Japan, and the Netherlands
September 17, 2026
The OECD has published updated arbitration profiles for the Netherlands, Australia, and Japan under the Multilateral
Read More
Japan: Cabinet approves food tax cut plan
September 16, 2026
Japan’s cabinet approved an outline on 15 September 2026 to reduce the consumption tax on food from 8% to 1% for two
Read More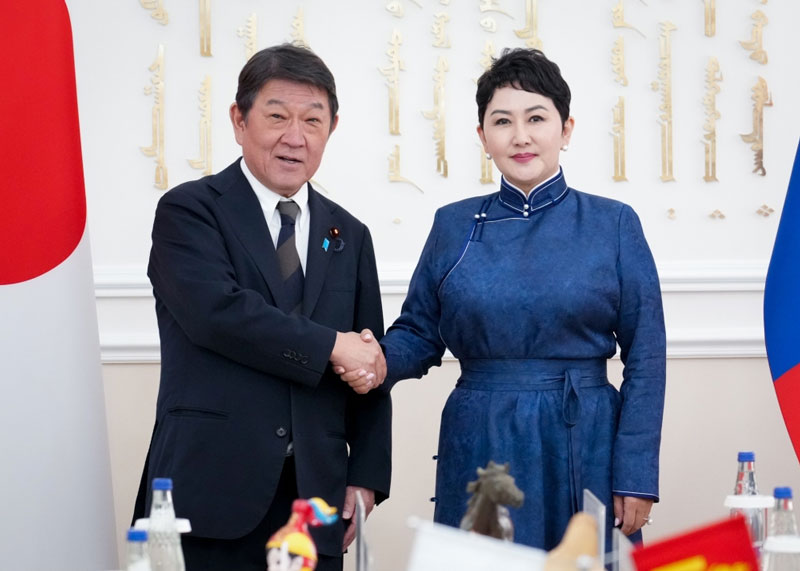
Japan, Mongolia advance income tax treaty negotiations
September 10, 2026
Japan and Mongolia, on 3 September 2026, agreed to advance discussions towards the conclusion of a bilateral income tax
Read More
Japan, Paraguay IPA to enter into force
September 07, 2026
The Agreement between Japan and Paraguay for the Investment Protection Agreement (IPA), signed on 5 December 2025,
Read More
Belgium: MoF clarifies treaty coverage of Japan’s 4% corporate defence tax
September 04, 2026
The Belgian Ministry of Finance confirmed that Japan’s 4% special corporate tax on defence, effective from 1 April
Read More
Australia: ATO publishes MoU with Japan on arbitration procedures
July 13, 2026
The Australian Taxation Office (ATO) has published a Memorandum of Understanding (MoU) with Japan, outlining the
Read More