


Japan’s National Tax Agency (NTA) has issued Frequently Asked Questions (FAQs) regarding transfer pricing (TP) documentation requirements in Japan. It addresses those questions that are likely to be of most interest to overseas headquartered Multinational enterprises with a Japanese subsidiary or branch. A key concern is a clarification on when the tax authorities may apply presumptive taxation (The tax authorities have the right to presume a transfer price and to reassess the taxable income accordingly) and use examinations of companies in the same industry (i.e., secret comparable) to estimate the amount of tax to be paid. This clarification may pointer a greater intent by the Japanese tax authorities to make use of those measures.s.


Related Posts
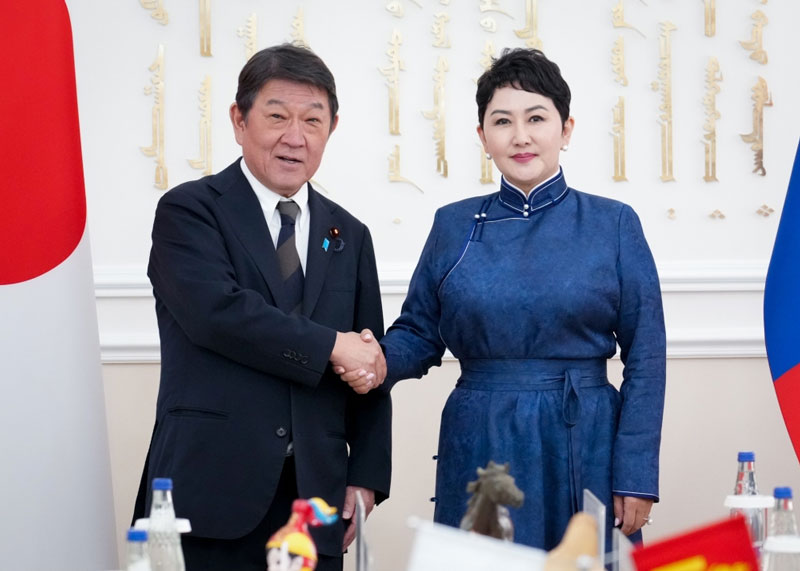
Japan, Mongolia advance income tax treaty negotiations
September 10, 2026
Japan and Mongolia, on 3 September 2026, agreed to advance discussions towards the conclusion of a bilateral income tax
Read More
Japan, Paraguay IPA to enter into force
September 07, 2026
The Agreement between Japan and Paraguay for the Investment Protection Agreement (IPA), signed on 5 December 2025,
Read More
Belgium: MoF clarifies treaty coverage of Japan’s 4% corporate defence tax
September 04, 2026
The Belgian Ministry of Finance confirmed that Japan’s 4% special corporate tax on defence, effective from 1 April
Read More
Australia: ATO publishes MoU with Japan on arbitration procedures
July 13, 2026
The Australian Taxation Office (ATO) has published a Memorandum of Understanding (MoU) with Japan, outlining the
Read More
Japan, Kyrgyzstan new income tax treaty enters into force
July 02, 2026
Japan's Ministry of Foreign Affairs has announced that the new income tax treaty with Kyrgyzstan will enter into force
Read More
Japan, Kyrgyzstan income tax treaty to enter into force in July
June 29, 2026
The Japan-Kyrgyzstan income tax treaty (2025) will enter into force on 26 July 2026, following the completion of the
Read More