


On 18 July 2018, the French tax authorities published instructions regarding Master / Local file in the context of transfer pricing documentation. As per the guidelines, the new documentation requirements apply for fiscal years beginning on or after 1 January 2018 and correspond to the OECD BEPS action 13.


Related Posts
France extends zero VAT treatment to air transport in Guadeloupe, Martinique
September 15, 2026
France has extended its 0% value added tax (VAT) rate to air transport services carried out in Guadeloupe and
Read More
Australia, France sign memorandum of understanding on arbitration under BEPS MLI
September 14, 2026
The Australian Taxation Office (ATO) has published a Memorandum of Understanding signed with France outlining the mode
Read More
France starts nationwide e-invoicing rollout for businesses
September 09, 2026
France's Directorate General of Public Finance began the nationwide rollout of business-to-business electronic
Read More
France updates guidance on VAT rate for cooling energy
September 01, 2026
France has clarified that the supply of cooling energy distributed through networks is subject to the reduced 5.5% rate
Read More France updates income tax reduction guidance for SME investments
September 01, 2026
France’s tax authority has updated its guidance on income tax reductions for investments in small and medium-sized
Read More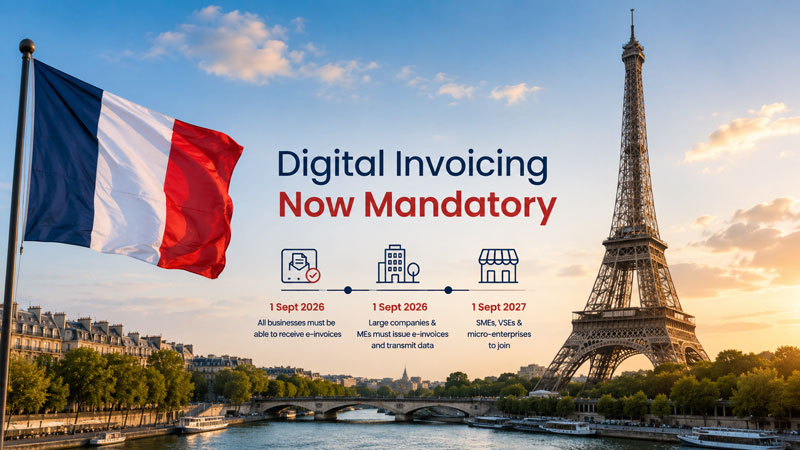
France: Ministry of Economy and Finance introduces mandatory e-invoicing
September 01, 2026
France has today introduced mandatory electronic invoicing and the transmission of transaction data to the tax
Read More