


On 13 May 2020, the tax authority published final guidelines regarding restrictions on interest deduction, including the amendments introduced by the Finance Law for 2019 to implement the EU Anti-Tax Avoidance Directive (ATAD). In accordance with the guide, the additional borrowing costs are deductible for the tax period during which they were incurred, but only up to 30% of the EBITDA and EUR 3 million safe harbor. The final guideline also permits a 75% deduction cost for stand-alone companies. These provisions apply to fiscal years beginning on or after 1 January 2019, with the exception of those relating to the special regime of net finance costs borne by independent companies that apply to fiscal years ending on or after December 31, 2019.


Related Posts
France starts nationwide e-invoicing rollout for businesses
France's Directorate General of Public Finance began the nationwide rollout of business-to-business electronic
Read More
France updates guidance on VAT rate for cooling energy
France has clarified that the supply of cooling energy distributed through networks is subject to the reduced 5.5% rate
Read More France updates income tax reduction guidance for SME investments
France’s tax authority has updated its guidance on income tax reductions for investments in small and medium-sized
Read More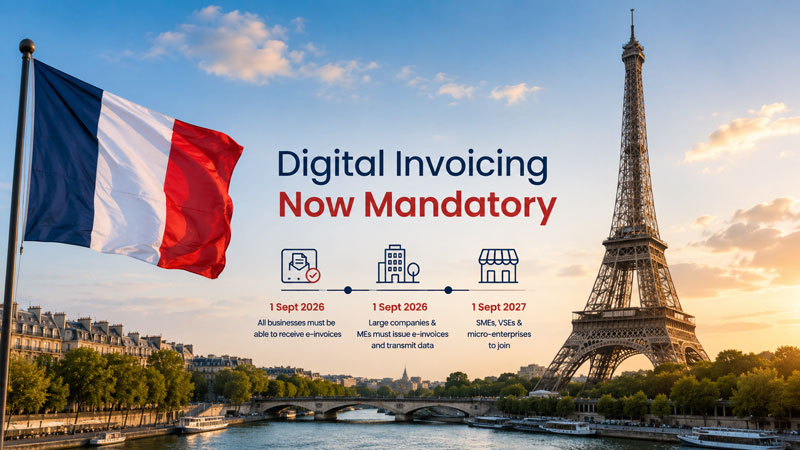
France: Ministry of Economy and Finance introduces mandatory e-invoicing
France has today introduced mandatory electronic invoicing and the transmission of transaction data to the tax
Read More
France introduces tax neutrality for enterprise restructuring
France has clarified, on 19 August 2026, the tax treatment of sole proprietorship restructuring where an individual
Read More
France strengthens tax incentives for investment, innovation, green industry
France’s tax system provides a broad range of incentives aimed at supporting investment, innovation, business
Read More